How did the segments perform?
Healthcare Solutions revenue rose about 14.4% to $49.0 million, driven by higher dental materials sales and more parts manufacturing volume. The company cites growth above 20% in both healthcare parts manufacturing and dental materials. Industrial Solutions grew about 3.9% to $50.3 million, or 7.7% excluding software divestitures, on higher printer and parts manufacturing sales.
Within industrial, Data Center Infrastructure grew strongly and Aerospace and Defense grew by more than 50%, while consumer-facing markets declined. The company says its four strategic markets, Med Tech, Dental, Aerospace and Defense, and Data Center Infrastructure, have posted strong double-digit growth over the first three quarters.
Why is there a net loss despite positive EBITDA?
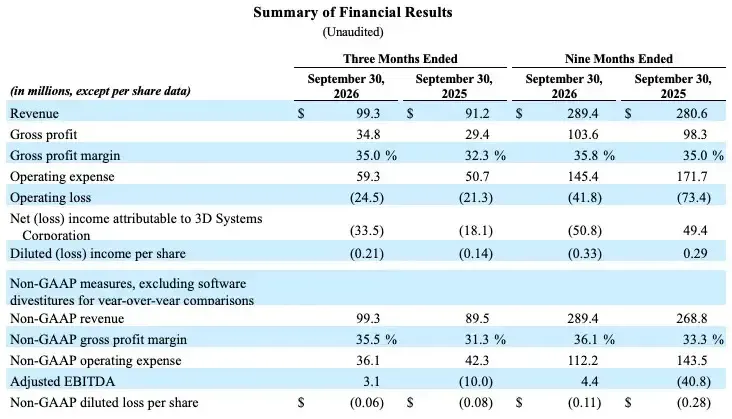
Gross margin rose to 35.0% from 32.3%, and the non-GAAP margin reached 35.5% from 32.5%. The company credits higher printer and parts volumes, product margin gains and the absence of some prior-year costs. Adjusted EBITDA improved by $13.9 million to $3.1 million.
The net loss attributable to the company grew by $15.5 million to $33.5 million. The company names litigation expense, an asset impairment charge, unfavourable foreign exchange and a worse tax result as the main causes.
What are the liquidity and outlook?
At 30 September 2026 the company held $120.5 million in cash and investments. Of its debt, $3.9 million matures in the fourth quarter of 2026 and $92.0 million in 2030.
For the fourth quarter, 3D Systems expects revenue of $100 to $103 million and Adjusted EBITDA between minus $2 million and zero. At the midpoint, full-year revenue growth would approach mid-single digits. The software divestitures covered Geomagic in April 2025 and 3DXpert and Oqton in October 2025, which affects year-on-year comparisons.